
Specialty
Reverse Mortgages
Turn a portion of your home equity into greater financial flexibility while continuing to own and live in your home.
Overview
A reverse mortgage can help eligible homeowners age 62 and older access a portion of their home equity without a required monthly principal and interest payment. Funds may be available as a lump sum, line of credit, monthly advances, or a combination depending on the program. The loan becomes due when the last borrower permanently leaves the home, sells it, or no longer meets the loan requirements.
Who It May Fit
Homeowners age 62 and older who want to explore using home equity to support retirement, improve monthly cash flow, refinance an existing mortgage, or purchase a different primary residence.
Potential Benefits
- No required monthly principal and interest payment while loan requirements are met
- Remain the owner of your home
- Flexible ways to receive available proceeds
- Proceeds are generally not considered taxable income; consult a tax advisor
- HECM for Purchase may help eligible buyers purchase a new primary residence
Important Considerations
- The home must remain the borrower’s primary residence
- Property taxes, homeowners insurance, maintenance, and applicable HOA dues must remain current
- Interest and loan charges accrue over time and reduce available equity
- HUD-approved counseling is required for FHA-insured HECM loans
- The loan becomes due when the last borrower sells, permanently moves out, or no longer meets loan requirements
FAQs
Next Step
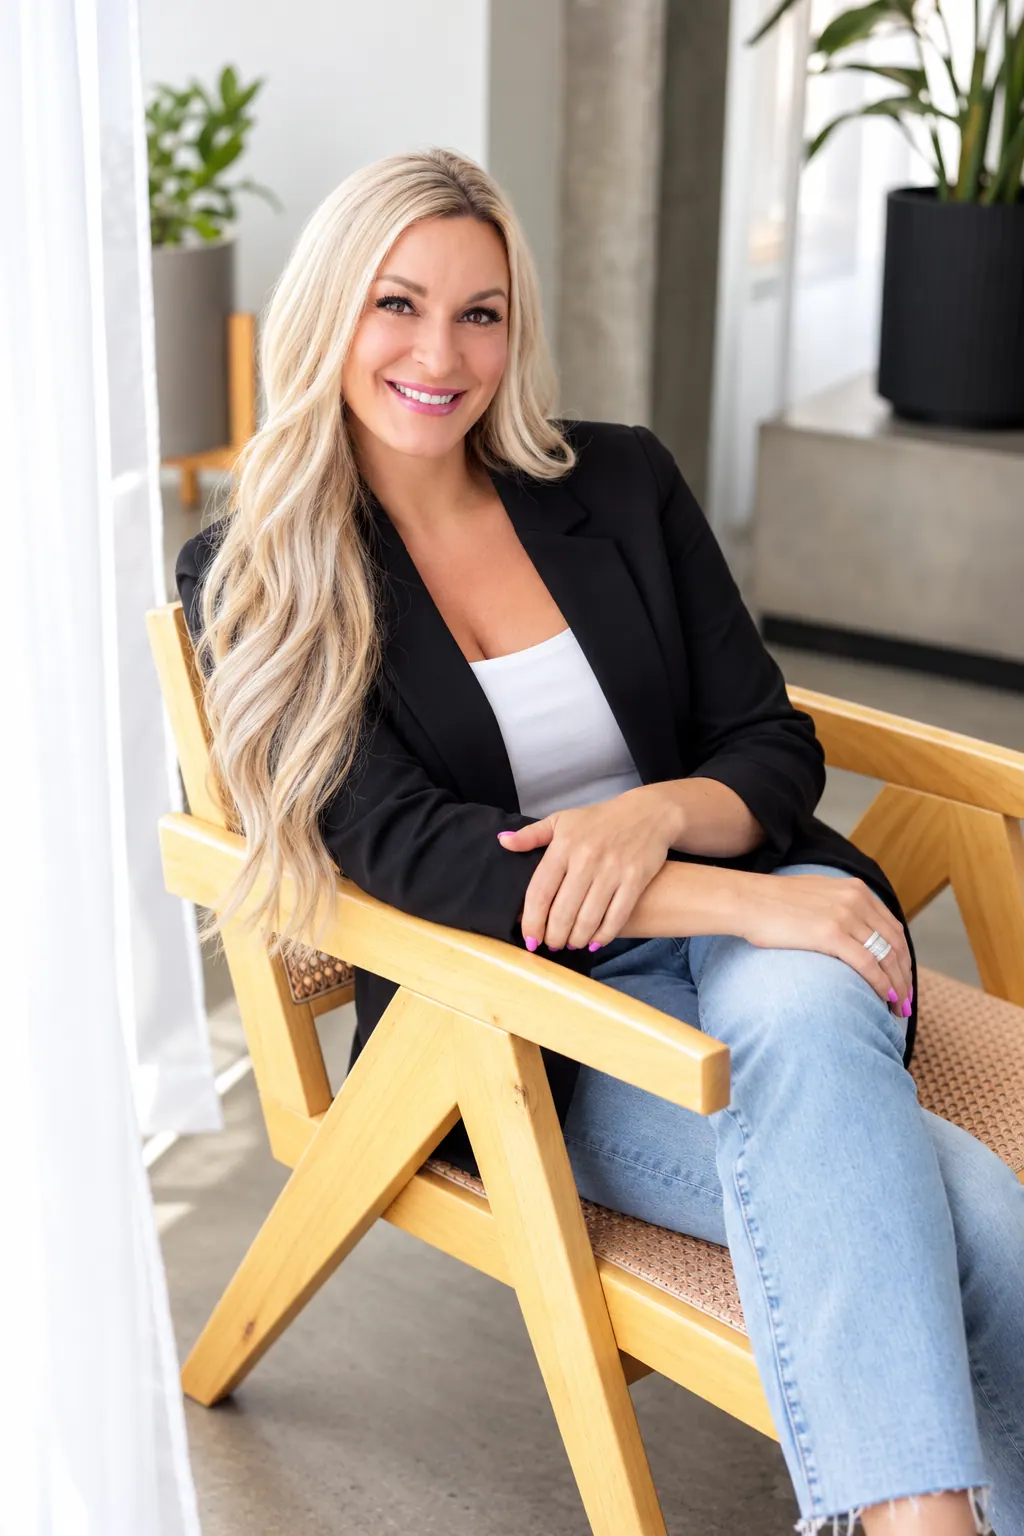
Talk to Kahren Oxner
Founder & CEO
Connect with Kahren to review eligibility, structure, and next steps.